Samsung led with 23% market share, driven by Galaxy Z Fold8 demand, despite a 3% annual shipment decline
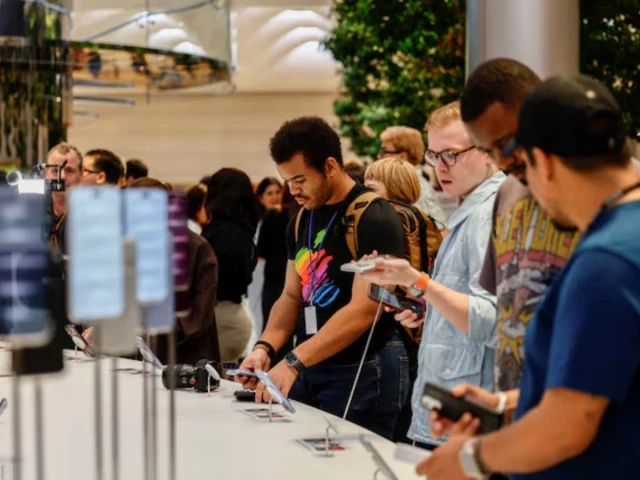
Customers look at the Apple iPhone 18 Pro and Apple iPhone 18 Pro Max at the Apple Fifth Avenue flagship store during the launch of the Apple iPhone 18 Pro and iPhone 18 Pro Max in New York City, US, September 18, 2026. REUTERS
Global smartphone shipments fell 20% on-year to their lowest third-quarter level since 2012, as soaring memory chip costs and supply shortages pressured manufacturers and pushed up prices, preliminary estimates from Counterpoint Research showed on Monday.
Rising prices for memory components as AI infrastructure projects corner supplies have driven up production costs and prompted manufacturers to raise retail prices, cut shipments and prioritise profitability over volumes.
“Consumers are holding on to their devices longer than estimated, increasingly considering refurbished devices and prioritizing higher-value devices,” said Counterpoint senior analyst Shilpi Jain.
Samsung retained its top position with a 23% market share, helped by demand for its Galaxy Z Fold8 series and stable component supplies for its mid-range devices. Shipments fell 3% from a year earlier during the quarter.
Read More: Microsoft plans huge deployment of its own AI chips, with an eye on saving costs
Apple’s market share reached 22%, crossing 20% for the first time in a third quarter, despite a year-on-year decline in shipments.
The absence of a base iPhone 18 model resulted in a smaller launch-month channel fill than the full iPhone 17 lineup a year earlier, Counterpoint said.
OPPO and vivo recorded shipment declines of more than 20%. Xiaomi saw a more than 30% fall, reducing its market share to 10% as the company cut exposure to lower-priced devices and some overseas markets to protect margins.
“The outlook for the remainder of 2026 remains challenging,” Counterpoint said.
“Production cuts, tighter portfolios, and greater focus on premium devices are likely to continue, while price-sensitive segments face further pressure from higher device prices and limited availability of components.”